Michael Vandi
Most lending teams already follow some version of a loan origination process, but if it’s not clear, repeatable, or fast, it costs time and deals. A loan origination system workflow adds structure, from the first borrower interaction to loan funding.
Clunky handoffs, missing borrower data, manual processes, and document verification delays often point to outdated lending workflows.
The right loan origination system (LOS) uses workflow automation, document management, and credit risk assessment to help teams process loan applications with fewer errors.
If you're working to improve your lending operations, this breakdown shows where delays happen and how to fix them.
TL;DR
A loan origination system workflow organizes lending from borrower inquiry through funding with defined stages, tasks, and decision points.
Automation helps modern financial institutions manage documents, application routing, compliance checks, and higher loan volumes.
Digital intake and timely updates enhance customer experience by making applications easier to complete and track.
Regular workflow reviews can uncover delays, duplicate work, and gaps between connected lending systems.
Addy adds mortgage-focused AI for pre-underwriting, document review, condition resolution, and borrower follow-ups within existing workflows.
What Is a Loan Origination System Workflow?
A loan origination system workflow is the digital version of your lending process, starting at borrower inquiry and ending at loan funding. It helps teams manage each step in one system instead of jumping between spreadsheets, emails, or manual checklists.
Loan origination software supports this workflow by automating repetitive tasks and keeping the process moving. It allows for faster handoffs, fewer delays, and better visibility into where each loan stands.
The core parts of a loan origination workflow include:
Defined stages - Clear checkpoints that move applications through the process.
Automated tasks - System-triggered actions like document routing, data checks, and approvals.
Rules-based logic - Application routing based on loan types, credit history, or risk flags. Requirements can vary for personal loans, auto loans, and commercial lending.
Collaboration points - Built-in coordination between loan officers, processors, and underwriters.
Audit trails - Full records of all actions for compliance and internal reviews.
This kind of setup helps lending teams handle more loan volume, catch issues early, and meet compliance and risk requirements without sacrificing speed or borrower experience.
Curious how your current process stacks up? Book a demo with Addy.
Key Stages in a Loan Origination System Workflow
To improve your workflow, start by defining each stage of the loan lifecycle. Here's a practical breakdown of every key step lenders typically follow, from pre-qualification through funding.
1. Pre-Qualification
Pre-qualification is a quick check to see if a borrower meets basic lending criteria. Loan officers gather initial borrower data, such as income and credit history, to determine early eligibility.
Automating this step helps lending teams quickly identify suitable applicants and filter out unqualified leads. It saves valuable time and lets teams focus on applicants with a realistic chance of approval.
2. Loan Application
The loan application process involves gathering detailed borrower data and financial documents. Borrowers submit income statements, identification, and other supporting paperwork required for formal review.
Simplifying the loan application process makes things smoother for borrowers. Modern loan origination systems can offer digital document uploads and user-friendly forms that reduce manual data entry and improve the overall borrower experience.
For online lenders, digital access also makes it easier for borrowers to submit applications and documents remotely.
3. Loan Processing
Loan processing is where lending teams carefully review borrower information and verify documents. Tasks include identity checks, income verification, and document accuracy reviews.
Using process automation for document handling and verification cuts manual errors and processing delays. It also helps the team stay organized and keeps required documents attached to the right loan file.
4. Underwriting
During underwriting, teams assess the borrower's risk level and ability to repay. Loan underwriters review financial data, credit reports, borrower history, and factors such as the debt-to-income ratio to determine loan eligibility.
Advanced analytics can help underwriters evaluate these factors alongside traditional credit scoring methods. Automation can also flag risk factors and relevant loan data for review before a decision is made.
5. Credit Decision
The credit decision stage is when lenders approve, conditionally approve, or reject loan applications. Accurate communication about loan terms, loan amount, and rates is especially important here.
A well-managed workflow helps borrowers receive updates on time. Consistent communication can ease borrower uncertainty and help lending teams avoid unnecessary delays or confusion.
6. Quality Control and Regulatory Compliance
Quality control involves checking that the loan process meets all regulatory compliance requirements. It includes verifying documentation accuracy and confirming that required lending and legal standards have been met.
A well-documented workflow provides comprehensive audit trails. Digital records make it easier for lenders to demonstrate regulatory compliance and respond to questions or issues during internal or external reviews.
7. Funding and Closing
The final stage includes preparing loan agreements, finalizing repayment schedules, and funding the approved loan. Lenders confirm all documents are accurate and complete, then complete loan disbursement to the borrower.
An organized workflow at this stage helps lenders catch last-minute document or funding issues. It helps lending teams close more loans quickly and accurately while keeping the final steps easier for borrowers and team members to follow.
What Lenders Gain by Improving Their Loan Origination Workflow
A disorganized workflow slows down lending operations and makes routine tasks harder to manage. Delays in document handling, unclear responsibilities, or missing borrower data can lead to longer approval times and frustrated borrowers.
Improving your workflow helps teams move faster, cut manual errors, and keep the loan process consistent. It also makes it easier to track where loans stand, catch issues early, and meet compliance requirements without extra back-and-forth.
An efficient loan origination system workflow allows lenders to:
Speed up loan approvals - Automated workflows and clear task routing help reduce turnaround time.
Improve customer experience - Faster updates and better communication keep borrowers informed and can improve borrower satisfaction.
Lower operating costs - Automation can cut the team hours devoted to repetitive tasks.
Improve compliance - Defined steps and audit trails make it easier to meet regulatory standards.
Each improvement adds up. Faster decisions, better data accuracy, and better coordination help lending institutions manage growing loan portfolios without adding extra work.
Help your team move faster with a more efficient workflow. Book a demo with Addy today!
Proven Ways to Improve Your Loan Origination Workflow
Improving your workflow starts with fixing the common issues that hold up applications. These usually include repetitive manual tasks, unclear roles, outdated tools, and missing data during reviews.
Here are four ways to build a more efficient loan origination workflow:
Automate repetitive tasks - Use loan origination software to handle data entry, document routing, and system checks, so your team can focus on decisions that need attention.
Review your workflow regularly - Set time aside to audit your process. Look for steps that cause delays, require duplicate work, or involve disconnected existing systems. For example, for credit unions, this can include checking how data passes between the LOS, core banking systems, and other financial systems.
Make tools easy to use - If your loan officers or borrowers are confused by the system, they’ll avoid using it. Clear layouts and simple interfaces help everyone stay on track.
Keep your process updated - Make sure your workflow reflects current regulatory requirements and internal policies. Outdated steps can lead to compliance issues and unnecessary delays.
Improvements at each stage support better communication and help teams manage higher volumes without sacrificing quality.
Make Loan Origination Easier at Every Step With Addy
Addy uses mortgage-focused AI agents to help lenders with pre-underwriting, condition resolution, and routine loan processing tasks. Instead of relying on fragmented tools or manual tasks, Addy works with the systems lenders already use, so teams can focus on decisions that need judgment.
Lenders can use Addy for loan-related document review, mortgage guideline checks, missing-document requests, and borrower communication. It works alongside a lender’s current technology without requiring a system replacement.
Addy has also expanded these workflows into ChatGPT. Its mortgage pre-underwriting app lets lenders and loan officers prepare pre-underwriting findings inside ChatGPT in roughly five minutes.
What Addy Helps You Do
With Addy, you can:
Process loans faster - Addy's AI agents review documents, assess loan information, and generate summaries in minutes.
Automate guideline checks - Addy can check loan files against 20,000+ mortgage policies and guidelines and flag issues for review.
Handle borrower follow-ups automatically - AI agents can contact borrowers when documents are missing, helping files continue through processing.
Generate custom-branded loan summaries - Addy pulls borrower information into summaries and updates them as new data becomes available.
Search deal data quickly - Loan officers can search borrower information and file data without digging through separate emails and documents.
Integrate with your existing tech stack - Addy connects with CRM, email, and other mortgage tools, including modern LOS platforms.
Cut manual errors and context switching - AI agents handle repetitive data extraction and validation, which can improve data integrity by avoiding repeated manual entry.
Real Results: How Sphinx Capital Cut Processing Time by 10x
Sphinx Capital, a nationwide real estate lender, used to spend up to an hour building loan summaries by pulling info from emails, documents, and internal tools.
Addy changed that.
By automating data collection and generating AI-powered summaries, they now complete the same task in under one minute.
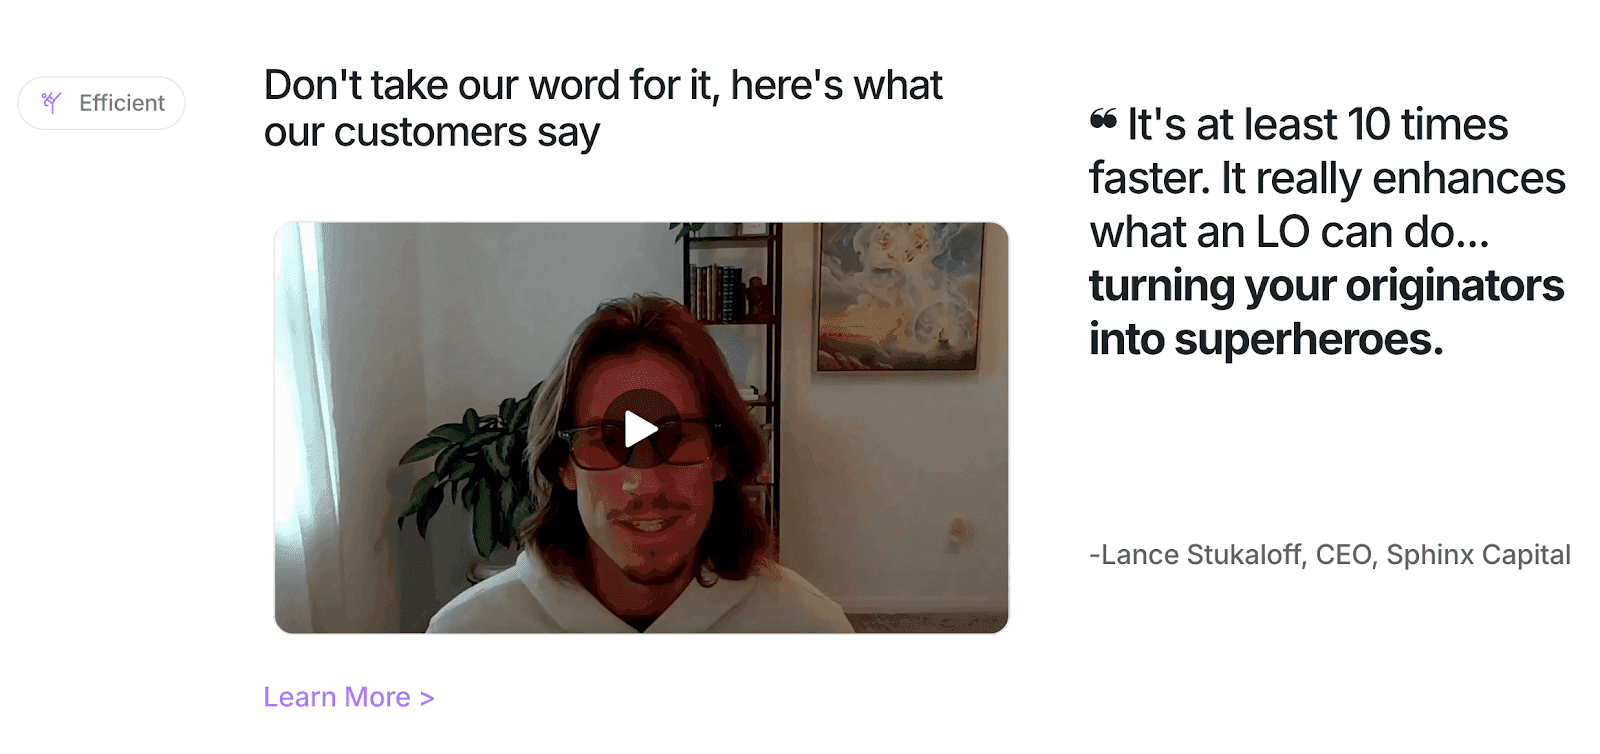
Addy helped their team shift focus from manual work to client relationships. With deal data centralized and follow-ups automated, they scaled their process without adding more headcount.
Loan officers using Addy spend more time with borrowers and less time checking boxes. With AI handling the busywork, teams can move faster, stay accurate, and deliver a better experience for every loan.
How Advanced Technology Improves LOS Workflows
A borrower submits their application, but key documents are missing. The loan processor follows up, but there’s a delay. Without the files, underwriting stalls. The borrower waits with no update and may start looking elsewhere.
This kind of slowdown is common when teams rely on disconnected tools and manual steps. Advanced technology helps by keeping tasks organized, reducing delays, and helping teams track what needs attention at each stage.
Here’s how modern tools improve loan origination workflows:
Captures borrower info directly from uploaded documents
Identifies risk earlier using credit history from credit bureaus and financial data
Assigns deals to the right team based on set rules
Shows loan status, borrower behavior, and next steps
Flags missing items or gaps based on current requirements
Platforms like Addy support lending teams with automation, task tracking, and document management that reduce delays and help teams manage files throughout the loan lifecycle. It’s about giving teams better tools so they can work faster and address issues before they hold up the file.
Use Addy to Build a Workflow That Doesn’t Break Under Pressure
A loan origination workflow should remain dependable when application volume rises, deadlines tighten, or files require extra attention. Each stage should give teams a practical way to keep applications progressing from intake through funding.
If you're evaluating loan management systems or refining your current workflow, Addy can help you identify where mortgage AI can add practical value. The goal is to apply automation where it fits the lending process, not add unnecessary complexity.
FAQs About Loan Origination System Workflow
What are the steps in the loan origination process?
The loan origination process typically includes pre-qualification, formal loan application, document collection, loan processing, underwriting, credit decision, and funding.
At each stage, teams assess the borrower's creditworthiness and review required information to support the approval process.
What are the functions of a loan origination system?
A loan origination system manages the process from borrower intake through funding. Key functions include document intake, identity verification, credit checks, data analysis, underwriting process support, compliance checks, and risk management.
These functions support operational efficiency by enabling lenders to manage applications and required tasks within a defined workflow.
How does a loan origination system help determine if a borrower qualifies?
A loan origination system helps determine qualification by reviewing income, credit history, assets, debt-to-income ratio, and required loan documents. It can compare that information with lender and program criteria during the underwriting process.
This helps teams apply qualification rules consistently and identify missing information before a credit decision.
What is the loan management system workflow?
A loan management system workflow typically covers post-funding activities such as loan servicing, payment processing, account updates, and portfolio monitoring. It can also help lenders track loan performance, maintain accurate records, and manage ongoing loan activity after disbursement.
Start closing more loans – Book your demo today
Stay ahead of the competition and discover how AI can accelerate your loan origination process, reduce manual work, and help you close more deals in less time. Book a demo today and start experiencing the future of lending.